Decoding Your Taxable Social Security Income: A Personal Journey
As you navigate the complexities of your annual tax return, one of the most common and often confusing areas you’ll encounter is the calculation of your Social Security taxable amount. It’s a crucial figure that directly impacts your overall tax liability, and understanding how it’s determined can save you money and alleviate stress. This article will serve as your personal guide, demystifying the process of calculating the portion of your Social Security benefits that may be subject to federal income tax. We’ll break down the key concepts, essential forms, and practical steps to ensure you accurately report this income.
When filing your taxes, understanding the taxable amount of Social Security benefits on Form 1040 is crucial for accurate reporting. For a comprehensive guide on this topic, you can refer to a related article that explains how to determine the taxable portion of your Social Security income and the implications it may have on your overall tax liability. To learn more, visit this informative article.
The Fundamentals of Social Security Taxability
Before diving into the calculations, it’s vital to grasp the underlying principles that govern whether your Social Security benefits are taxed. It’s not a straightforward “yes” or “no” answer; rather, it depends on your total income from all sources. The Social Security Administration (SSA) itself doesn’t tax your benefits. Instead, it’s the Internal Revenue Service (IRS) that may include a portion of your benefits as taxable income if your overall financial picture reaches certain thresholds.
What Constitutes “Total Income” for Tax Purposes
The IRS uses a specific definition of “combined income” to determine the taxability of your Social Security benefits. This isn’t simply your adjusted gross income (AGI) as you might see on other parts of your tax return. Your combined income includes your AGI, plus any non-taxable interest you may have received, and half of your Social Security benefits. This broader definition is designed to capture a more comprehensive view of your financial resources to assess your ability to pay taxes.
Understanding the Thresholds for Taxation
The IRS has established specific income thresholds that trigger the taxation of Social Security benefits. These thresholds are the same for all filing statuses (single, married filing jointly, etc.) but are often a point of confusion.
Thresholds for Single, Head of Household, and Qualifying Widow(er) Filers
If you file as single, head of household, or a qualifying widow(er), your Social Security benefits may be taxable if your combined income is more than \$25,000.
Thresholds for Married Individuals Filing Separately
The rules are slightly different for those who are married and file separate tax returns. If you are married and file a separate return, you will generally have to pay tax on your Social Security benefits if your combined income is more than \$32,000. However, it’s important to note that if you lived with your spouse at any time during the year, you generally cannot use these higher thresholds and may have to pay tax on your benefits even if your combined income is less than \$32,000.
Thresholds for Married Couples Filing Jointly
For married couples filing jointly, the thresholds are higher, reflecting the combined income of both spouses. If your combined income is more than \$32,000, but not more than \$44,000, then up to 50% of your Social Security benefits may be taxable. If your combined income is more than \$44,000, then up to 85% of your Social Security benefits may be taxable.
The “Up to” Clause: Why Not All Benefits Are Always Taxed
You’ll notice the IRS uses the phrase “up to” when referring to the percentage of your benefits that may be taxable. This is a critical distinction. Even if you fall within the taxable income thresholds, it doesn’t automatically mean that the maximum percentage of your benefits will be taxed. The actual taxable amount is calculated based on your specific combined income. The lower your combined income within a taxable bracket, the smaller the portion of your Social Security benefits will be subject to tax.
Calculating Your Combined Income: The First Crucial Step

The cornerstone of determining your taxable Social Security amount is accurately calculating your combined income. This figure is the sum of your adjusted gross income (AGI), any non-taxable interest income, and half of your Social Security benefits. Getting this calculation right is paramount, as it dictates which tax bracket your Social Security benefits fall into.
Pinpointing Your Adjusted Gross Income (AGI)
Your AGI is a foundational number on your tax return. It’s your gross income minus certain specific deductions, often referred to as “above-the-line” deductions. You can find your AGI on your Form 1040, U.S. Individual Income Tax Return, typically on the first page. It’s important to use the AGI from your most recently filed federal income tax return. If you haven’t filed yet, you’ll need to calculate it first.
Identifying Non-Taxable Interest Income
Non-taxable interest income refers to interest earned from sources that are exempt from federal income tax. The most common example is interest earned on tax-exempt bonds, such as municipal bonds issued by state and local governments. While this interest isn’t taxed, it still counts towards your combined income for the purpose of taxing your Social Security benefits. You can usually find this information on your Form 1099-INT if you have received such income.
Determining Half of Your Social Security Benefits
The Social Security Administration (SSA) will send you a Form SSA-1099, Social Security Benefit Statement, each year. This form details the total amount of Social Security benefits you received during the tax year. To calculate your combined income, you’ll take the gross amount of benefits shown on this form and divide it by two. This is the figure you’ll use in the combined income calculation.
Navigating Form 1040 and Its Supporting Schedules
The IRS provides specific forms and worksheets to help you accurately calculate the taxable portion of your Social Security benefits. The primary forms you’ll interact with are Form 1040 itself and Schedule 1 (Form 1040), and potentially Schedule B (Form 1040) if you have significant interest income. The detailed calculation will often involve using an IRS worksheet.
Locating the Relevant Lines on Form 1040
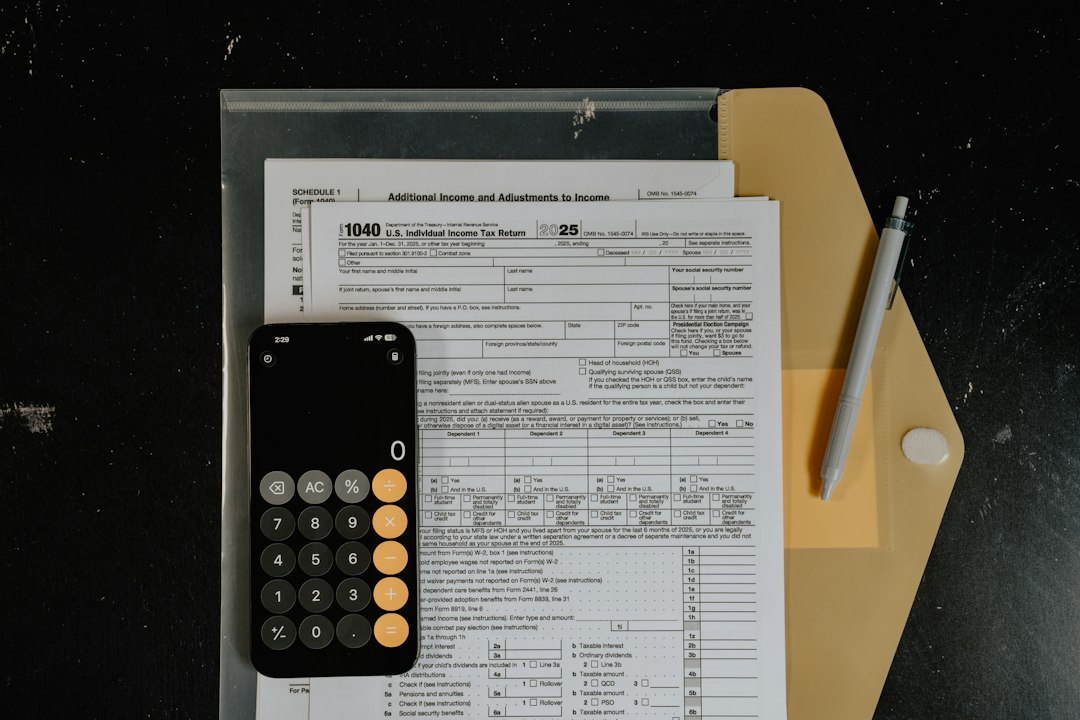
When you’re filling out your Form 1040, you’ll find lines dedicated to reporting Social Security benefits. Line 6a of the 2023 Form 1040 asks for “Social security benefits,” and Line 6b asks for “Taxable amount.” This is where the magic, or at least the calculation, happens. You’ll initially report the gross amount of your benefits on Line 6a. The taxable amount on Line 6b will be the result of the calculations we’re discussing.
Utilizing Schedule 1 (Form 1040) for Additional Income
Schedule 1 (Form 1040), Additional Income and Adjustments to Income, is where you’ll report certain types of income that are not directly reported on the main Form 1040. This includes things like unemployment compensation and other taxable income that might contribute to your AGI. While your Social Security benefits are reported directly on Form 1040, the components of your AGI that you’ll use to calculate your combined income are often detailed on Schedule 1.
Understanding the Social Security Benefits Worksheet
The IRS provides a dedicated worksheet within the Form 1040 instructions to help you calculate the taxable portion of your Social Security benefits. This worksheet is your best friend in this process. It systematically guides you through the steps of calculating your combined income and then determining how much of your benefits falls into the different taxable tiers. It’s crucial to follow this worksheet meticulously.
Step 1: Calculate Your Combined Income
The first step within the worksheet involves calculating your combined income. You’ll add your AGI (from Line 11 of Form 1040 for 2023), any non-taxable interest income, and half of your Social Security benefits. Ensure you’re using the correct figures from your tax return and SSA-1099.
Step 2: Determine the Taxable Amount Based on Filing Status and Combined Income
Once you have your combined income, the worksheet will direct you to compare it to the applicable thresholds based on your filing status. It will then help you determine whether 0%, 50%, or 85% of your Social Security benefits are potentially taxable. The worksheet will then further refine this by calculating the exact dollar amount of your taxable benefits.
The Role of Schedule B (Form 1040) for Interest Income
If you have significant interest income, particularly from taxable sources that contribute to your AGI, you might need to use Schedule B (Form 1040), Interest and Ordinary Dividends. This schedule provides a place to list all your interest-bearing accounts and the amounts received. The total taxable interest from Schedule B will then be carried over to your Form 1040 and factored into your AGI.
When filing your taxes, understanding the taxable amount of Social Security benefits on Form 1040 is crucial for accurate reporting. Many taxpayers are unaware that a portion of their Social Security income may be subject to taxation, depending on their overall income level. For a deeper dive into this topic, you can explore a related article that provides valuable insights on tax implications and strategies for managing your taxable income. Check it out here to enhance your understanding of how to navigate these complexities effectively.
Performing the Actual Calculation: A Step-by-Step Walkthrough
| Filing Status | Provisional Income Threshold 1 | Provisional Income Threshold 2 | Taxable Percentage of Social Security Benefits |
|---|---|---|---|
| Single, Head of Household, Qualifying Widow(er) | 25,000 | 34,000 |
Below Threshold 1: 0% Between Threshold 1 and 2: Up to 50% Above Threshold 2: Up to 85% |
| Married Filing Jointly | 32,000 | 44,000 |
Below Threshold 1: 0% Between Threshold 1 and 2: Up to 50% Above Threshold 2: Up to 85% |
| Married Filing Separately (lived with spouse) | Generally 85% taxable regardless of income | ||
Let’s walk through a hypothetical scenario to illustrate the calculation process. Remember, you’ll be using the IRS worksheet for the most accurate results, but understanding the logic behind it is key.
Scenario Setup: A Married Couple Filing Jointly
Imagine you and your spouse are married and filing jointly. For the tax year, you received \$30,000 in Social Security benefits. Your adjusted gross income (AGI) for the year was \$40,000, and you had \$1,000 in taxable interest income from a savings account.
Step 1: Calculate Combined Income
Using the figures from our scenario:
- AGI: \$40,000
- Non-taxable Interest: \$0 (for simplicity in this example, assume no non-taxable interest)
- Half of Social Security Benefits: \$30,000 / 2 = \$15,000
Combined Income = AGI + Non-taxable Interest + Half of Social Security Benefits
Combined Income = \$40,000 + \$0 + \$15,000 = \$55,000
Step 2: Apply Thresholds and Determine Taxable Percentage
Now, we compare the combined income of \$55,000 to the thresholds for married individuals filing jointly:
- Up to \$32,000: 0% taxable
- \$32,001 to \$44,000: Up to 50% taxable
- Over \$44,000: Up to 85% taxable
Since our combined income of \$55,000 is over \$44,000, our Social Security benefits are potentially taxable at up to 85%.
Step 3: Calculate the Taxable Amount
The IRS worksheet has a structured method to calculate the exact taxable amount, which considers the different tiers. For a combined income over \$44,000 for married couples filing jointly, the calculation involves:
- First Tier: All of your Social Security benefits up to \$32,000 are taxed at 85%.
- Second Tier: Any additional Social Security benefits above \$32,000 are taxed at 85%.
However, the actual calculation within the worksheet is more nuanced to prevent taxing more than is legally required. It essentially determines how much of your income falls into each of the taxable “buckets.”
Let’s illustrate a simplified version of the worksheet’s logic for our \$55,000 combined income:
- Base Amount: Your AGI plus your non-taxable interest = \$40,000 + \$0 = \$40,000.
- Taxable Portion of Benefits: The worksheet calculates the taxable portion based on how much of your combined income exceeds the lower thresholds.
For combined income over \$44,000, the worksheet will essentially look at the portion of your benefits that, when added to your other income, pushes you into higher tax brackets. A simplified way to think about the upper limit of taxation for this scenario is:
- Maximum Taxable Amount: Your combined income up to the highest threshold (\$44,000 for this filing status) plus the amount of your benefits that, when added to your other income, does not exceed the total taxable amount calculation.
Let’s use the IRS worksheet’s approach more directly. The worksheet helps calculate the “amount of benefits subject to tax.”
For married couples filing jointly with combined income over \$44,000:
The worksheet will first consider the benefits that fall into the 50% taxable tier.
Taxable amount from the 50% tier = The lesser of:
a) 50% of your benefits (\$15,000)
b) \$32,000 minus your AGI + non-taxable interest (if this is a positive number)
In our case, \$32,000 – \$40,000 = -\$8,000. Since this is negative, this tier doesn’t apply for determining the taxable amount above the 50% calculation.
Then, it moves to the 85% tier.
The worksheet effectively calculates the portion of your benefits that, when added to your AGI and non-taxable interest, falls within the taxable thresholds.
A common outcome for combined income above \$44,000 is that a significant portion of the benefits will be taxed at the 85% rate.
Let’s assume, for the sake of illustration and following the IRS worksheet’s methodology, that the calculation results in:
- Portion of benefits taxed at 50%: Let’s say \$12,000. (This is a simplified illustration; the actual worksheet is more precise).
- Portion of benefits taxed at 85%: The remaining benefits.
The worksheet is designed to ensure you don’t pay tax on more than 85% of your total benefits.
Let’s try a different approach, focusing on the IRS’s stated thresholds and the worksheet’s logic:
If your combined income is over \$44,000 (married filing jointly):
- Determine your “Provisional Income.” This is your AGI + Non-taxable interest + 50% of your SS benefits.
Provisional Income = \$40,000 + \$0 + \$15,000 = \$55,000.
- Compare Provisional Income to Taxable Thresholds.
- If Provisional Income is \$32,000 or less, 0% is taxable.
- If Provisional Income is between \$32,001 and \$44,000, up to 50% is taxable.
- If Provisional Income is over \$44,000, up to 85% is taxable.
Since our Provisional Income is \$55,000, up to 85% of our benefits are taxable. The worksheet then calculates the exact taxable amount.
The worksheet first calculates the taxable amount if your combined income were between \$32,001 and \$44,000.
Amount subject to tax = (Your combined income – \$32,000) \* 0.50
Amount subject to tax = (\$55,000 – \$32,000) \ 0.50 = \$23,000 \ 0.50 = \$11,500
Then, it calculates the taxable amount if your combined income were over \$44,000.
Amount subject to tax = (\$32,000 – \$25,000) \ 0.50 + (Your combined income – \$44,000) \ 0.85
This formula is for single filers. For married filing jointly, the formula is slightly different and more complex, aiming to find the portion of benefits that, when added to other income, falls into taxable ranges.
Let’s simplify by looking at the maximum taxable amount within the 85% tier.
The IRS worksheet essentially calculates the portion of your benefits that, when added to your AGI, pushes you beyond the lower thresholds.
For married filing jointly with combined income > \$44,000:
The taxable portion of your benefits is the lesser of:
a) 85% of your total Social Security benefits
b) The sum of:
\$10,500 (This is the difference between \$44,000 and \$32,000, multiplied by 50%, plus the difference between \$32,000 and \$25,000 for single filers, but for married filing jointly, it’s a calculation related to the total income that gets you to the 85% bracket.)
AND
Your combined income in excess of \$44,000.
Let’s use a direct application of the worksheet’s final steps.
For married filing jointly with combined income > \$44,000:
The taxable amount is the lesser of:
- 85% of your Social Security benefits (\$15,000 \* 0.85 = \$12,750)
- The sum of:
- \$10,500 (This represents the maximum taxable amount from the 50% bracket for single filers, and a similar concept applies here to bridge the gap to the 85% bracket for joint filers.)
- PLUS: Your combined income exceeding \$44,000 (\$55,000 – \$44,000 = \$11,000)
So, the amount from option 2 is \$10,500 + \$11,000 = \$21,500.
Since \$12,750 (option 1) is less than \$21,500 (option 2), the taxable amount of your Social Security benefits is \$12,750.
This \$12,750 would be reported on Line 6b of your Form 1040. This \$12,750 is then added to your other taxable income, increasing your overall tax liability for the year.
Common Pitfalls and How to Avoid Them
Even with clear guidelines, taxpayers can sometimes make mistakes when calculating their taxable Social Security benefits. Being aware of these common pitfalls can help you avoid them.
Overlooking Non-Taxable Interest
As we’ve discussed, non-taxable interest, even though it’s not taxed on its own, contributes to your combined income. It’s easy to forget about interest earned from municipal bonds or other tax-exempt sources, but failing to include it can lead to an underestimation of your combined income and, consequently, an underreporting of your taxable Social Security benefits. Always review all your income sources.
Misinterpreting “Combined Income”
The definition of “combined income” is specific to Social Security benefit taxation. It’s not the same as your AGI. You need to remember to add back half of your Social Security benefits and any non-taxable interest to your AGI to arrive at the correct figure for this calculation.
Using Incorrect Thresholds for Your Filing Status
The IRS has different income thresholds based on your filing status. Double-check that you are using the correct thresholds for single, married filing jointly, head of household, or married filing separately. Using the wrong thresholds can lead to an incorrect determination of whether your benefits are taxable and at what percentage.
Not Using the Official IRS Worksheet
While you can understand the concepts, the IRS worksheet is specifically designed to handle the nuances of the calculation, including the different taxable tiers and limitations. Relying on estimations or simplified formulas can lead to errors. Always download and use the most current Social Security Benefits Worksheet from the IRS website or the instructions for Form 1040.
Forgetting to Report All Income Sources
Your tax return requires you to report all income. If you have other taxable income besides your Social Security benefits and interest, such as wages, pensions, or investment gains, these all contribute to your AGI and, therefore, your combined income. Ensure your entire financial picture is accounted for.
Seeking Professional Assistance When Needed
While this article aims to demystify the process, there are situations where seeking professional help is advisable. If your tax situation is complex, if you have multiple income streams, or if you’re unsure about any aspect of the calculation, consulting a tax professional is a wise decision.
When Your Tax Situation Becomes Complicated
If you have significant investments, foreign income, self-employment income, or other complex financial elements, the calculation of your combined income can become more intricate. A tax professional can navigate these complexities and ensure accurate reporting.
Understanding the Impact on Your Overall Tax Liability
The taxable portion of your Social Security benefits adds to your overall taxable income. This can push you into a higher tax bracket or increase your tax liability. A tax advisor can help you understand this impact and explore potential tax-saving strategies.
Ensuring Accuracy and Compliance
The IRS takes tax compliance seriously. Errors in reporting Social Security benefits can lead to audits, penalties, and interest. A qualified tax professional can ensure your return is accurate and compliant with all IRS regulations. They can also help you identify any potential deductions or credits you might be eligible for.

Your 401(k) Withdrawal Can Make More of Your Social Security Taxable
FAQs
What is Form 1040 Social Security taxable amount?
Form 1040 Social Security taxable amount refers to the portion of your Social Security benefits that may be subject to federal income tax. This amount is calculated based on your total income and filing status.
How is the taxable amount of Social Security benefits determined?
The taxable amount of Social Security benefits is determined by adding one-half of your Social Security benefits to your other income, including tax-exempt interest. If this total exceeds a certain base amount, a portion of your Social Security benefits may be taxable.
Who is required to report the taxable amount of Social Security benefits on Form 1040?
If your total income exceeds the base amount set by the IRS, you are required to report the taxable amount of your Social Security benefits on Form 1040. This applies to individuals who receive Social Security benefits and have other sources of income.
What is the base amount for determining the taxable amount of Social Security benefits?
The base amount for determining the taxable amount of Social Security benefits is $25,000 for single filers and $32,000 for married couples filing jointly. If your total income exceeds these thresholds, a portion of your Social Security benefits may be taxable.
Are there any strategies to reduce the taxable amount of Social Security benefits?
There are some strategies that can help reduce the taxable amount of Social Security benefits, such as managing other sources of income, timing withdrawals from retirement accounts, and maximizing deductions and credits. Consulting with a tax professional can also provide personalized advice on minimizing the tax impact on your Social Security benefits.