You’re probably here because you’re feeling the weight of debt, or perhaps you’re just curious about how it whispers—or screams—in your ear when you’re about to make a purchase. It’s a constant companion, isn’t it? That nagging feeling, that internal debate that flares up the moment you see something you desire, but also the bills you owe. Debt doesn’t just sit in a separate ledger; it actively shapes the very fabric of your spending decisions, influencing what you buy, when you buy it, and even how you feel about the act of buying itself. This isn’t just about numbers; it’s about psychology, about habit, and ultimately, about the freedom—or lack thereof—you experience in your financial life.
When you’re in debt, the world of consumer goods takes on a different hue. That shiny new gadget, that trendy piece of clothing, that spontaneous weekend getaway—they aren’t just opportunities for enjoyment anymore. They are potential additions to your existing financial burden, and that thought fundamentally changes how you assess their true worth.
The Immediate Gratification vs. Long-Term Consequences Equation
You see something you want. Your mind, for a fleeting second, conjures up the pleasure of owning it. But then, almost instantaneously, another image flashes: your credit card statement, your loan repayment schedule. The joy of the immediate gratification is instantly pitted against the long-term sting of carrying more debt.
The Discounted Future Self
Your future self is the one who will actually be paying for that purchase. But in the present moment, your future self often feels like a stranger, someone you can guilt or burden without immediate consequence. This psychological distance allows you to prioritize your current desires over your future financial well-being, especially when the debt is already substantial. The “out of sight, out of mind” mentality applies heavily here.
The Opportunity Cost of Debt Repayment
Every dollar you spend on non-essential items when you have debt is a dollar that could have gone towards paying down that debt. This is the opportunity cost. You might not explicitly calculate it, but it exists. That $50 impulse buy is $50 less that can chip away at your principal, meaning you’ll be paying interest on that $50 for longer, accumulating more over time. This realization can make you acutely aware of the true cost of every purchase, even small ones.
The Erosion of “Wants” into “Needs” (or Perceived Needs)
Debt can also subtly shift your perception of what you truly need. When you’re constantly feeling deprived due to debt repayment, you might start to rationalize purchases as necessities, even if they are purely wants.
The “Treat Yourself” Justification
After a long week of working to pay off debt, the temptation to “treat yourself” becomes incredibly strong. This often leads to spending that isn’t truly necessary, but it feels justified as a reward for enduring financial hardship. The problem is, these “treats” can perpetuate the cycle of debt if not carefully managed. You’re essentially using money you don’t have to soothe the pain of not having money.
The Social Pressure and Comparison Trap
In a consumer-driven society, there’s immense pressure to keep up with trends and maintain a certain lifestyle. When you’re in debt, this pressure can feel even more intense. You might feel compelled to buy certain items or engage in certain activities to avoid feeling left out or judged by others, even if it means taking on more debt. This is a particularly insidious aspect, as it externalizes your spending decisions rather than grounding them in your own financial reality.
Understanding how debt affects spending decisions is crucial for managing personal finances effectively. For a deeper insight into this topic, you can explore the article available at How Debt Influences Consumer Behavior. This article delves into the psychological and economic factors that shape spending habits in the context of debt, providing valuable information for anyone looking to improve their financial literacy and decision-making skills.
The Psychological Impact: Fear, Anxiety, and the Urge to Avoid
Debt isn’t just a financial burden; it’s an emotional one. The constant worry, the sleepless nights, and the pervasive sense of being trapped can profoundly influence your psychological state, which in turn dictates your spending habits.
The Paralyzing Effect of Fear
Fear of accumulating more debt, or fear of not being able to meet your obligations, can lead to a kind of financial paralysis. This can manifest in several ways when it comes to your spending.
The “Freeze” Response: Avoiding All Spending
For some, the anxiety of debt is so overwhelming that they tend to avoid spending altogether, even on things they genuinely need or would enjoy. This is a form of the “freeze” response to a perceived threat. They become overly cautious, hoarding money out of fear, which can sometimes hinder their ability to invest in things that could improve their financial situation in the long run (like education or a more reliable vehicle).
The Impulse Spending “Release Valve”
Paradoxically, for others, the anxiety of debt can lead to the opposite: impulsive spending as a way to escape or momentarily numb the stress. This is a classic coping mechanism where individuals seek a temporary high or distraction from their worries. The thrill of a new purchase, however fleeting, can provide a brief respite from the constant pressure of debt. Unfortunately, this often exacerbates the problem.
The Erosion of Confidence and Self-Esteem
Being in debt can chip away at your confidence and self-esteem. You might feel like you’re failing or not in control of your life, and this can impact your willingness to make confident spending decisions.
The Hesitation to Invest in Yourself
If you feel a general lack of confidence due to debt, you might be hesitant to invest in yourself. This could mean forgoing opportunities for professional development, further education, or even just investing in your health and well-being. The fear that you might not be able to afford these things, or that they won’t pay off, can prevent you from making crucial steps towards a better future.
The Avoidance of Financial Planning and Budgeting
The same lack of confidence can lead to an avoidance of financial planning and budgeting altogether. The thought of confronting the extent of your debt can be so daunting that you’d rather not look at it, which naturally impacts how you decide to spend your money. You’re operating in a fog, making decisions without a clear understanding of your financial landscape.
The Budgetary Constraints: The Tangible Limitations Imposed by Debt
Beyond the psychological and perceptual shifts, debt imposes very real, tangible limitations on your spending. Your budget becomes a tightrope, and every dollar spent is a careful calculation.
The Prioritization of Essential Expenses
When debt is a significant factor, your spending decisions become heavily weighted towards essentials. Rent, utilities, groceries, and minimum debt payments take precedence over everything else. This leaves very little room for discretionary spending.
The “Needs vs. Wants” Dichotomy Becomes Stark
The age-old “needs vs. wants” debate transforms from a philosophical exercise into a daily survival strategy. You can no longer afford to blur the lines. A new pair of shoes might be a want, but so is a reliable car to get you to work. The decision becomes a stark prioritization, where the potential consequences of foregoing a need are far more severe than the temporary disappointment of denying a want.
The Sacrifice of Hobbies and Leisure
Many hobbies and leisure activities are often the first to be sacrificed when you’re trying to manage debt. The cost of memberships, equipment, or even just the time and money required for a hobby can seem like an unaffordable luxury. This can lead to a significant reduction in your quality of life, impacting your overall happiness and well-being.
The Interest Payments: The Hidden Cost That Drains Your Wallet
The interest you pay on your debt is a significant drain on your resources. This recurring expense eats into your disposable income, directly impacting how much you have left to spend on other things.
The “Debt Snowball” or “Debt Avalanche” Impact
When you’re actively trying to pay down debt, your spending decisions are often dictated by your chosen repayment strategy. Whether you’re focusing on paying off the smallest balances first (snowball) or the highest interest rates (avalanche), your budget will be meticulously crafted to allocate as much as possible towards debt reduction. This means every other spending decision is viewed through the lens of whether it deviates from this primary goal.
The Amplification of Every Purchase
Because a portion of your income is already earmarked for interest payments, every other purchase you make feels amplified. That $100 you spend on entertainment isn’t just $100; it’s $100 plus the interest you’ll continue to accrue on the debt that money could have paid down. This awareness can make even small purchases feel like a significant financial undertaking.
The Long-Term Outlook: Shifting Priorities and the Quest for Financial Freedom
The impact of debt on your spending decisions isn’t just about the present; it also profoundly influences your long-term outlook and your aspirations for the future.
The Postponement of Major Life Goals
Debt can force you to postpone or even abandon significant life goals that require substantial financial investment.
The Delay of Homeownership
Buying a home is a dream for many, but significant debt can make this goal seem insurmountable. Lenders are often hesitant to approve mortgages for individuals with high debt-to-income ratios, and even if approved, the monthly mortgage payments in addition to existing debt can be overwhelming. This can lead to years of renting, feeling like you’re not building equity in your own future.
The Postponement of Starting a Family or Early Retirement
The financial strain of debt can also impact decisions about starting a family or planning for retirement. The uncertainty of your financial future can make you hesitant to take on the added expenses of children, and the need to constantly service debt can make it impossible to save adequately for retirement. The dream of early retirement, or even a comfortable retirement, can seem like a distant fantasy.
The Re-evaluation of Lifestyle and Consumerism
The experience of living with debt can lead to a fundamental re-evaluation of your lifestyle and your relationship with consumerism.
The Embrace of Frugality and Minimalism
For many, the hardship of debt leads to an embrace of frugality and minimalism. They learn to live with less, to find joy in experiences rather than possessions, and to appreciate the value of money. This can be a powerful and liberating shift, even after the debt is gone.
The Shift Towards Experiences Over Material Goods
When the allure of material possessions has been dulled by the burden of debt, many find themselves prioritizing experiences. Travel, learning new skills, spending time with loved ones—these become more valuable than accumulating more things. This shift often leads to a more fulfilling and less materialistic life, regardless of your financial status.
Understanding how debt influences spending decisions is crucial for effective financial management. Many individuals find themselves in a cycle where their debt limits their ability to make purchases, leading to a more conservative approach to spending. This dynamic can create stress and impact overall well-being. For further insights into the relationship between debt and financial behavior, you can explore a related article that delves deeper into these concepts at How Wealth Grows.
The Path to Liberation: Making Conscious Spending Choices
| Metric | Description | Impact on Spending Decisions | Example |
|---|---|---|---|
| Debt-to-Income Ratio | Percentage of monthly income that goes toward debt payments | Higher ratio limits discretionary spending and increases caution in purchases | 35% debt-to-income ratio may reduce ability to buy non-essential items |
| Credit Card Utilization | Amount of credit used compared to total credit limit | High utilization can lead to reduced credit score and more conservative spending | Utilizing 80% of credit limit may cause spending cutbacks |
| Monthly Debt Payments | Total amount paid monthly toward debts | Higher payments reduce available funds for other expenses and discretionary spending | Paying 500 monthly on loans limits budget for entertainment |
| Psychological Stress Level | Emotional impact of carrying debt | Increased stress can lead to impulsive or restrained spending behaviors | Debt stress causing either overspending or extreme frugality |
| Access to Credit | Availability of additional credit lines or loans | Limited access may force prioritization of essential spending only | Denied loan applications leading to reduced spending flexibility |
Understanding the profound impact of debt on your spending decisions is the first step towards regaining control and making more conscious choices. It’s about recognizing the subtle influences and actively working to counteract them.
Developing Financial Awareness and Mindfulness
The key to overcoming the negative impacts of debt is to cultivate financial awareness and mindfulness in your spending habits.
The Power of the “Pause” Button
Before making any purchase, especially those that are not essential, implement a “pause” button. Give yourself 24 hours, or even just a few minutes, to reflect on the purchase. Ask yourself: Do I truly need this? Can I afford it without further burdening myself? Will this purchase bring me lasting joy or just temporary satisfaction?
Tracking Your Spending Diligently
The most effective way to understand where your money is going is to track your spending diligently. Use budgeting apps, spreadsheets, or even a simple notebook. Seeing the reality of your financial outflow can be a powerful motivator for change and a crucial tool for identifying areas where you can cut back.
Strategic Debt Reduction and Financial Planning
The ultimate goal is to reduce and eventually eliminate your debt. This requires a strategic approach and a commitment to financial planning.
Creating a Realistic Budget and Stick to It
A realistic budget is your roadmap to financial freedom. It needs to account for your income, your essential expenses, your debt payments, and a small allowance for discretionary spending. The key is to create a budget that is achievable and to hold yourself accountable to it.
Exploring Debt Consolidation or Refinancing Options
If your debt is significant, explore options like debt consolidation or refinancing. These strategies can help you lower your interest rates, simplify your payments, and potentially reduce the overall cost of your debt. This can free up more money for both essential spending and accelerated debt repayment.
Ultimately, your spending decisions are a reflection of your financial health and your priorities. Debt casts a long shadow, but by understanding its impact, you can begin to step out of that shadow and into a future of financial freedom and conscious, deliberate spending. The journey may be challenging, but the rewards—peace of mind and true control over your finances—are immeasurable.
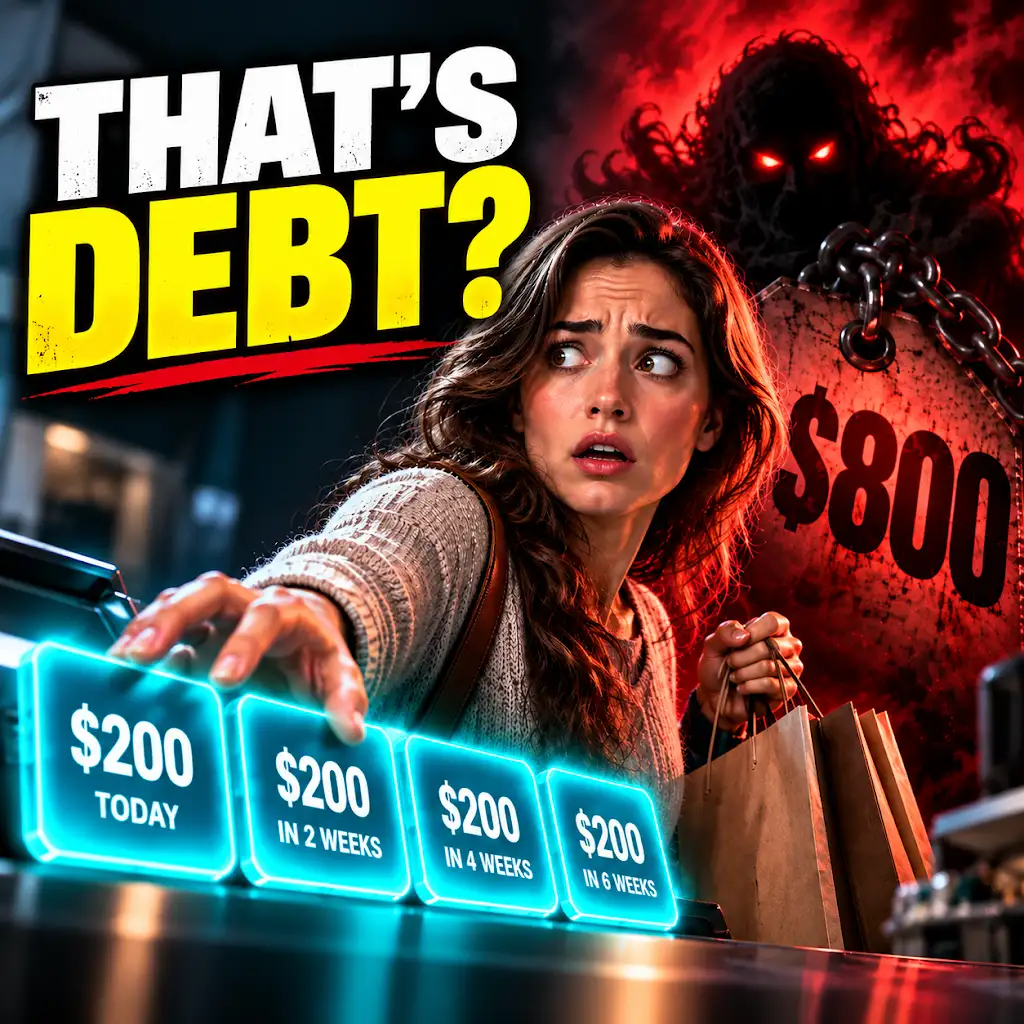
Why $800 Doesn’t Feel Like $800 Anymore
FAQs
1. How does debt impact spending decisions?
Debt can limit the amount of disposable income available for spending on goods and services, as a portion of income must go towards debt repayment.
2. Can high levels of debt lead to decreased consumer spending?
Yes, high levels of debt can lead to decreased consumer spending as individuals may prioritize debt repayment over discretionary purchases.
3. What are some ways in which debt can influence spending habits?
Debt can influence spending habits by causing individuals to be more cautious with their money, avoid taking on additional debt, and prioritize paying off existing debts.
4. How does debt affect long-term financial goals?
Debt can hinder progress towards long-term financial goals by diverting funds towards interest payments and away from savings or investments that could help achieve those goals.
5. Are there strategies to manage debt and maintain healthy spending habits?
Yes, strategies such as creating a budget, prioritizing debt repayment, and seeking financial counseling can help individuals manage debt and make more informed spending decisions.