You’ve probably heard the saying, “Cash is king.” While that might hold true for a quick purchase or a small emergency fund, when you’re talking about building your total retirement wealth, its role is more nuanced. It’s not about hoarding piles of physical bills, but rather understanding how readily available funds and strategic cash management can be powerful tools in your long-term financial arsenal. You might be surprised to learn that cash, in its various forms and strategic uses, plays a surprisingly vital role in ensuring you have the robust retirement nest egg you deserve. It’s a foundational element that, when wielded wisely, can significantly amplify the effectiveness of your other retirement savings strategies.
The Foundation of Financial Security: Emergency Funds and Cash Reserves
Think of your emergency fund as the bedrock of your entire financial life, especially when you’re planning for a distant goal like retirement. Without a solid emergency fund, any unexpected event – a job loss, a major medical expense, a sudden home repair – can derail your retirement savings plans. You might be forced to dip into your investment accounts, potentially selling low during a market downturn, or even liquidation of assets that were meant to grow over decades. This is where having accessible cash becomes paramount. It’s not just about comfort; it’s about financial resilience. Your emergency fund acts as a buffer, absorbing life’s unexpected shocks without compromising your long-term financial trajectory.
Quantifying Your Safety Net: How Much Cash is Enough?
Determining the appropriate size of your emergency fund is a crucial first step. There’s no one-size-fits-all answer, as it depends heavily on your individual circumstances, risk tolerance, and stability of your income. Generally, financial experts recommend having three to six months’ worth of essential living expenses readily available. This means calculating your absolute necessities: mortgage or rent payments, utilities, food, insurance premiums, and minimum debt payments. If your income is variable or you have dependents, you might consider extending this to nine or even twelve months. The goal is to have enough cash to cover your most critical expenses for an extended period, giving you peace of mind and preventing you from making impulsive, detrimental financial decisions. You need to be realistic about your spending and factor in potential increases in costs, such as utilities or insurance, during uncertain times.
Where to Keep Your Cash: Accessibility and Safety
The location of your emergency fund is as important as its size. You want it to be easily accessible when you need it, but not so accessible that you’re tempted to spend it on non-emergencies. High-yield savings accounts (HYSAs) are an excellent choice for this purpose. They offer competitive interest rates, which can help your cash keep pace with inflation somewhat, and they provide FDIC insurance, ensuring your principal is protected up to the legal limits. Money market accounts are another option, often offering slightly higher interest rates than traditional savings accounts and similar safety features. While certificates of deposit (CDs) can offer higher interest rates, their lack of liquidity can make them unsuitable for an emergency fund, as you’ll typically incur penalties for early withdrawal. The key is to find a balance between earning a modest return and ensuring immediate access. You don’t want your emergency money locked away in an investment that takes time to liquidate.
When considering how cash fits into total retirement wealth building, it’s essential to understand the broader context of financial planning. A related article that delves into this topic can be found at How Wealth Grows, which discusses various strategies for accumulating wealth over time. This resource highlights the importance of balancing liquid assets, such as cash, with other investment vehicles to create a robust retirement portfolio that can withstand market fluctuations and provide financial security in later years.
Strategic Cash Deployment: Opportunities for Growth and Stability
Beyond emergency funds, cash plays a crucial role in strategic financial moves that can boost your retirement wealth. This isn’t about idle cash sitting in a checking account earning nothing; it’s about deploying cash strategically during specific market conditions or for planned financial actions. Thinking ahead and having cash reserves available at the right moment can lead to significant advantages in your retirement planning. It’s about being prepared to capitalize on opportunities that arise and to execute your plans with financial flexibility.
Market Dips: Buying Low and Increasing Your Holdings
One of the most powerful ways cash can contribute to your retirement wealth is by allowing you to “buy low” during market downturns. When stock markets experience corrections or bear markets, asset prices become depressed. If you have cash reserves on hand, you can take advantage of these lower prices to acquire more shares of your favored investments at a discount. This is a fundamental principle of investing: buying assets when they are undervalued and selling when they are overvalued. Having cash available means you don’t have to wait for your next paycheck or sell other assets to seize these opportunities. This proactive approach can significantly compound your returns over the long term, as those discounted shares have greater potential for appreciation when the market recovers. It requires discipline and a long-term perspective, but the rewards can be substantial.
Rebalancing Your Portfolio: Maintaining Your Desired Asset Allocation
Portfolio rebalancing is a critical strategy for managing risk and ensuring your investments remain aligned with your retirement goals. Over time, some of your investments will grow faster than others, causing your asset allocation to drift from your target. For example, if your stocks have performed exceptionally well, they might now represent a larger percentage of your portfolio than you originally intended, increasing your risk exposure. Rebalancing involves selling some of the outperforming assets and buying more of the underperforming ones to bring your portfolio back to your desired mix. You might also use cash to facilitate this rebalancing. If stocks have outpaced bonds, you might sell stocks and use the cash to buy more bonds. Conversely, if bonds have lagged, you might sell bonds and use that cash to buy more stocks. This systematic approach helps you stay disciplined and avoid chasing market trends.
Planned Purchases and Large Expenses
There are times when you might have planned large purchases or expenses that could impact your retirement savings if not adequately funded. This could include anything from a down payment on a property that you intend to rent out for retirement income, to funding a significant educational endeavor for a child that could free up your future resources. Having cash readily available for these planned events ensures you don’t have to disrupt your long-term investment strategy. It allows you to meet these financial obligations without compromising your retirement nest egg. Furthermore, having cash available for planned renovations on a retirement property or to cover unexpected, but anticipated, healthcare costs in your later years provides a sense of control and security.
The Role of Cash in Fixed-Income Strategies

While often associated with growth investments like stocks, cash also plays a significant role within fixed-income strategies, particularly for those nearing or in retirement. It’s not about earning exciting returns, but about stability, predictability, and ensuring you have access to funds when you need them most, without the volatility of the market. Your approach to cash in this phase shifts towards preserving capital and providing a reliable income stream.
Short-Term Bonds and Cash Equivalents: Preserving Capital
For retirees or those very close to retirement, preserving capital becomes a primary objective. This is where short-term bonds and cash equivalents come into play. While not strictly cash, these instruments are highly liquid and offer minimal price fluctuation compared to longer-term bonds or stocks. Think of them as very safe, short-term parking spots for your money that offer a slightly better return than a basic savings account. They are ideal for funds you anticipate needing in the short to medium term, ensuring that their value isn’t subject to significant market swings. This can include funds designated for upcoming expenses or a portion of your retirement income that you want to keep exceptionally secure.
Income Generation Through Cash Flow and Liquidity
In retirement, you need a reliable source of income to cover your living expenses. Cash reserves and highly liquid investments can be crucial for generating this income flow. You might draw income from your cash reserves or from the interest and dividends generated by your short-term fixed-income holdings. The key is to have a predictable and stable income stream that you can rely on. This allows you to avoid selling off your long-term growth assets during unfavorable market conditions. It provides a psychological buffer, knowing that your day-to-day expenses are covered by stable, readily available funds, reducing the stress associated with market fluctuations. Your cash strategy in retirement is about creating a consistent financial tide that supports your lifestyle.
Balancing Cash with Investment Growth: The Art of Asset Allocation
The ultimate goal for most people is to build substantial retirement wealth, and this invariably involves investing in assets that have the potential for growth. However, the role of cash is not to compete with these growth assets, but to complement them. It’s about finding the right balance, the optimal asset allocation, that suits your risk tolerance, time horizon, and financial goals. Too much cash can hinder growth, while too little can leave you vulnerable.
Understanding Your Risk Tolerance and Time Horizon
Your personal financial situation dictates how much cash you should hold versus how much you should invest. If you have a long time horizon until retirement, you can generally afford to take on more investment risk, meaning you might hold a smaller percentage of your total wealth in cash and a larger percentage in growth-oriented assets like stocks. Conversely, if retirement is just around the corner, or if you have a low risk tolerance, you’ll likely want a larger allocation to cash and more conservative investments to protect your accumulated savings. Consider your comfort level with market volatility. Are you someone who can sleep soundly during a market downturn, or does it cause you significant anxiety? Your answer will heavily influence your cash allocation strategy.
Diversification Beyond Cash: The Importance of Other Asset Classes
While cash is essential for security and strategic opportunities, it’s crucial to remember that it typically offers low returns, especially after accounting for inflation. To build significant retirement wealth, you need to embrace other asset classes that have historically provided higher returns over the long term. This includes stocks, bonds, real estate, and potentially alternative investments. Diversification across these different asset classes is key. It means spreading your investments among various types of assets, industries, and geographies to reduce overall risk. If one asset class performs poorly, others may perform well, helping to cushion the impact on your total portfolio. Cash, in this context, acts as a stabilizing force within a well-diversified portfolio, rather than the primary engine of growth.
When considering how cash fits into total retirement wealth building, it’s essential to understand the role of liquidity and its impact on financial security during retirement. For a deeper exploration of this topic, you can read a related article that discusses various strategies for managing cash within your overall retirement plan. This resource provides valuable insights into balancing cash reserves with investments to optimize your wealth growth. To learn more, check out this informative piece on wealth building strategies.
The Psychological Impact of Cash Holdings
| Component | Role in Retirement Wealth | Typical Allocation (%) | Advantages | Considerations |
|---|---|---|---|---|
| Cash & Cash Equivalents | Liquidity and safety; emergency fund and short-term needs | 5-15 | Low risk, easy access, stable value | Low returns, inflation risk |
| Bonds & Fixed Income | Income generation and capital preservation | 30-50 | Steady income, lower volatility than stocks | Interest rate risk, lower growth potential |
| Stocks & Equities | Growth and wealth accumulation | 40-60 | Higher returns over long term | Market volatility, risk of loss |
| Real Estate & Alternatives | Diversification and potential income | 5-15 | Inflation hedge, income potential | Illiquidity, market risk |
Beyond the purely financial aspects, the amount of cash you hold can have a profound psychological impact on your retirement planning journey. It can influence your decision-making, your stress levels, and your overall confidence in your financial future. It’s about the feeling of security that readily available funds can provide, and how that security can empower you to make better, more rational financial choices.
Reducing Financial Stress and Anxiety
One of the most significant psychological benefits of maintaining adequate cash reserves is the reduction of financial stress and anxiety. Knowing you have a safety net to fall back on in times of unexpected need can be incredibly liberating. This peace of mind allows you to approach your retirement planning with a clearer head, making decisions based on long-term goals rather than short-term fears. This is particularly important as you near retirement, where uncertainty about income and expenses can be a major source of worry. A well-funded emergency fund or accessible cash reserves can significantly alleviate these concerns, allowing you to enjoy your retirement with greater confidence.
Empowering Disciplined Decision-Making
When you have sufficient cash on hand, you are less likely to be forced into making impulsive or emotionally driven financial decisions. For instance, during a market downturn, if you’re not reliant on selling investments to cover immediate needs, you can resist the urge to panic sell. This discipline is crucial for long-term investment success. Similarly, having cash available for planned opportunities, like buying a property or making a strategic investment, allows you to act decisively and capitalize on favorable situations. Your cash reserves empower you to be a more strategic and less reactive investor, which is a cornerstone of building lasting retirement wealth. It gives you the leverage to choose when and how you engage with the market, rather than being dictated by necessity.
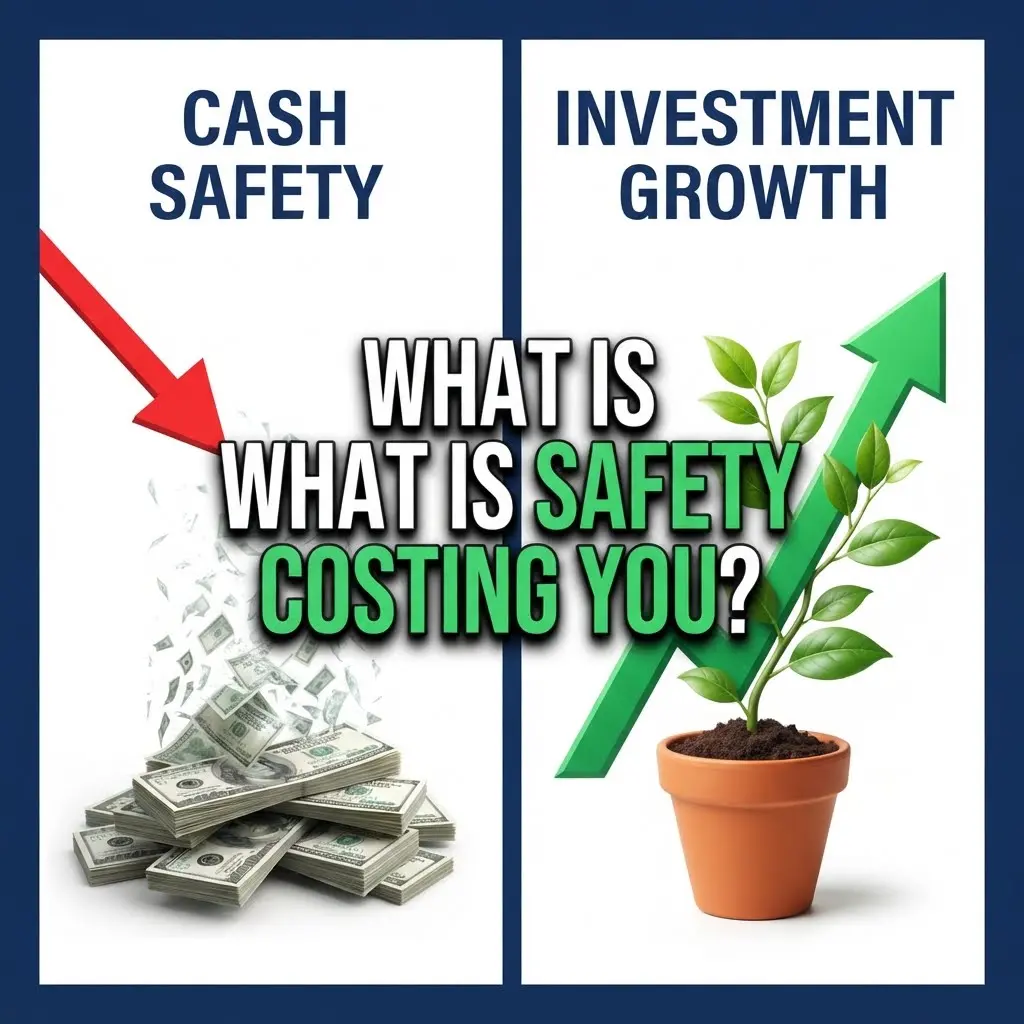
The 4% Retirement Mistake That’s Secretly Costing You Thousands
FAQs
1. How does cash play a role in total retirement wealth building?
Cash is an important component of total retirement wealth building as it provides liquidity and stability. Having cash on hand allows retirees to cover unexpected expenses without having to dip into their investments, which can help protect their long-term financial goals.
2. Should retirees hold a significant amount of cash in their retirement portfolio?
While having some cash in a retirement portfolio is important for emergencies and short-term needs, holding too much cash can be detrimental to long-term wealth building. Cash typically earns lower returns compared to other investments like stocks and bonds, so retirees should strike a balance between liquidity and growth potential.
3. How can retirees optimize the role of cash in their retirement wealth building strategy?
Retirees can optimize the role of cash in their retirement wealth building strategy by creating a cash reserve for emergencies and short-term expenses, while also investing the rest of their portfolio in a diversified mix of assets to generate higher returns over the long term.
4. What are some common sources of cash for retirees to build their retirement wealth?
Common sources of cash for retirees to build their retirement wealth include savings accounts, money market accounts, certificates of deposit (CDs), and short-term bonds. Retirees can also consider selling assets or downsizing their homes to generate additional cash for their retirement portfolio.
5. How can retirees protect their cash holdings from inflation risk?
To protect their cash holdings from inflation risk, retirees can consider investing in inflation-protected securities like Treasury Inflation-Protected Securities (TIPS) or diversifying their portfolio with assets that have historically outpaced inflation, such as stocks or real estate. It’s important for retirees to balance the need for liquidity with the goal of preserving purchasing power over time.