You’ve seen them everywhere. Those little charges, popping up on your bank statement or credit card bill, each one seemingly insignificant. A dollar here, five dollars there. They’re the silent architects of your spending habits, the invisible strings tugging at your wallet. You might dismiss them as pocket change, but the psychology behind these microtransactions is far more profound than you realize. Understanding this power isn’t just about recognizing where your money goes; it’s about understanding the intricate workings of your own mind and how it can be influenced, for better or worse.
The fundamental appeal of microtransactions lies in their perceived lack of impact. When you’re faced with a decision to spend $100, your brain immediately engages in a cost-benefit analysis. You weigh the value of what you’re getting against the significant depletion of your funds. It feels like a real sacrifice. But a $2 purchase? That hardly registers as a blip on your financial radar. This psychological phenomenon, often referred to as cognitive ease or reduced friction, makes the decision to spend almost effortless.
The Anchor of Perception: How Small Amounts Feel Smaller
Your brain doesn’t operate in a vacuum. It uses anchors and comparisons to make sense of the world, including your finances. When you’re accustomed to seeing larger expenses, a $3 charge feels minuscule by comparison. It’s like looking at a vast ocean and then a small puddle; your perception of the puddle’s size is dramatically altered by the context of the ocean. This anchoring effect means that even though the cumulative sum of these small payments can be substantial, each individual transaction feels trivial.
The Discounting of Future Consequences
Another key psychological driver is our tendency to delay gratification. When the reward is immediate and the cost feels negligible, the long-term consequences are easily discounted. You might think, “It’s only $5, what’s the harm?” You’re not considering the fact that this $5, repeated dozens of times a month, could contribute to a much larger bill or prevent you from saving for a more significant goal. This present bias, where immediate rewards are prioritized over future gains, makes microtransactions incredibly seductive.
The Illusion of Control: Feeling “Smart” About Small Spends
Sometimes, you might even feel like you’re being savvy by opting for a cheaper, smaller option. Think about choosing a small coffee over a large one, or buying a digital download instead of a physical copy. These small savings can create a sense of accomplishment and control over your spending, even if the actual financial impact is minimal. This self-perception of frugality can be a powerful motivator, making you more amenable to other small purchases.
The psychology behind small monthly payments can significantly influence consumer behavior and financial decision-making. For an in-depth exploration of this topic, you can refer to a related article that discusses how the perception of affordability impacts spending habits and financial planning. This article provides valuable insights into the mental triggers that make small payments appealing, ultimately affecting our purchasing choices. To read more, visit this link.
The Gamification of Spending: Turning Transactions into Rewards
Modern commerce has become increasingly adept at gamifying the act of spending. Microtransactions are often at the heart of these strategies, transforming mundane purchases into engaging experiences. This is where the power of variable reinforcement comes into play, a concept deeply rooted in behavioral psychology.
Loot Boxes and Micro-Aims: The Thrill of the Unknown
Video games have been pioneers in this arena. You’ve likely encountered “loot boxes” or similar in-game purchases. The appeal isn’t just in getting a specific item; it’s in the uncertainty of the reward. You don’t know exactly what you’ll get, and that element of surprise, combined with the small, recurring cost, can be incredibly addictive. Each purchase is a gamble, a mini-thrill that keeps you coming back for more. This taps into your brain’s dopamine reward system, making you associate the act of spending with pleasure and anticipation.
Subscription Services: The “Set It and Forget It” Trap
Subscription services, from streaming platforms to curated boxes of goodies, often operate on the principle of microtransactions. You sign up, and then a small monthly fee is automatically debited. This “set it and forget it” model is psychologically brilliant. It removes the need for an active decision each month. Your brain becomes accustomed to the regular charge, and the effort required to cancel often outweighs the perceived benefit of saving that small amount. It’s a form of habit formation that can lead to unconscious overspending.
In-App Purchases: The Seamless Integration of “Needs”
Mobile applications, in particular, have mastered the art of the microtransaction. You download a free app, and then suddenly, you find yourself needing “coins” to unlock new features, remove ads, or progress in a game. These purchases are seamlessly integrated into the user experience, often requiring just a tap or two. The frictionless nature of these transactions, combined with the immediate gratification they offer, makes them incredibly potent. You might tell yourself you’re only buying a few coins, but those few coins quickly add up.
The Psychological Biases That Fuel Microtransaction Success

Beyond the immediate allure, a host of ingrained psychological biases are actively exploited by the architects of microtransactions. Understanding these biases is crucial to recognizing when you’re being subtly influenced.
The Endowment Effect: Owning Even a Small Piece
Once you’ve made even a small investment in something – be it a digital asset in a game or a premium feature in an app – you begin to develop a sense of ownership. This is the endowment effect. You’re less likely to part with it, even if the monetary cost was minimal. This can lead you to justify further microtransactions to “complete” your ownership or enhance what you already possess.
The Scarcity Principle: The Fear of Missing Out (FOMO)
Limited-time offers, daily deals, and exclusive microtransactions tap directly into your fear of missing out (FOMO). When something is presented as scarce or time-sensitive, your brain perceives it as more valuable, even if the actual value is questionable. The urgency created by scarcity bypasses rational decision-making, pushing you to make impulsive purchases to avoid the feeling of being left out.
The Bandwagon Effect: Seeing Others Do It
If you see your friends or peers engaging in certain microtransactions, you’re more likely to follow suit. This is the bandwagon effect or social proof. The belief that “everyone else is doing it” can override your own reservations. In online communities, this can be particularly powerful, as you’re constantly exposed to the spending habits of others, normalizing and encouraging similar behaviors.
The Cumulative Impact: When Small Add Up to Big Problems

The most insidious aspect of microtransactions is their cumulative impact. Individually, they seem insignificant. Collectively, they can drain your finances, derail your savings goals, and even lead to financial distress. You might not notice the steady drip of water wearing away a stone, but over time, it makes a significant difference.
The Erosion of Savings: The Invisible Drain
Your savings account is often the silent victim of microtransactions. That $10 a week spent on virtual currency or small digital goods might not seem like much, but over a year, that’s over $500. This is money that could have been invested, saved for a down payment, or used for a more meaningful experience. The opportunity cost of these small, seemingly harmless purchases is often overlooked.
The Debt Spiral: A Slippery Slope
For some, microtransactions can be a slippery slope leading to debt. If you’re not actively tracking these small charges, they can easily accumulate on a credit card. The low barrier to entry means you might rack up hundreds of dollars in small, impulse purchases without realizing it until the bill arrives. Then, you’re not just paying for the items; you’re paying interest on them, further exacerbating the problem. This can be a significant contributor to a debt spiral, where you’re constantly trying to pay off past spending with future earnings.
The Psychological Toll: Guilt and Regret
Beyond the financial strain, the constant drain of microtransactions can take a psychological toll. You might experience guilt and regret when you finally tally up your spending, especially if it conflicts with your financial goals. This can lead to feelings of inadequacy and a loss of control, creating a negative feedback loop that makes it harder to break the habit. The cognitive dissonance between your desire to be financially responsible and your actual spending behavior can be very stressful.
The psychology behind small monthly payments can significantly influence consumer behavior, making it easier for individuals to commit to purchases without feeling the immediate financial burden. This concept is explored in detail in a related article that discusses how breaking down larger expenses into smaller, manageable payments can lead to increased spending and satisfaction. For more insights on this topic, you can read the full article here: How Wealth Grows. Understanding these psychological triggers can help both consumers and businesses navigate the complexities of financial decision-making.
Reclaiming Your Financial Agency: Strategies to Combat Microtransaction Temptation
| Metric | Description | Example | Psychological Impact |
|---|---|---|---|
| Perceived Affordability | How small payments feel more manageable than lump sums | Paying 20 monthly vs. 240 upfront | Reduces purchase hesitation and increases willingness to buy |
| Payment Frequency | Number of payments made over time | Monthly, weekly, or bi-weekly payments | More frequent small payments can feel less burdensome |
| Anchoring Effect | Initial price influences perception of subsequent payments | Showing original price before monthly payment | Small payments seem like a better deal compared to anchor |
| Commitment Level | Psychological commitment to ongoing payments | Subscription services with monthly fees | Can increase perceived value but also risk of cancellation |
| Discount Perception | How discounts affect willingness to pay monthly | 10% off if paid monthly vs. lump sum | Encourages opting for monthly payments over lump sum |
| Loss Aversion | Fear of losing money influences payment preference | Trial periods with monthly payments | Small payments reduce perceived risk of loss |
The good news is that you are not powerless against the allure of microtransactions. By understanding the psychology at play, you can develop strategies to reclaim your financial agency and make more intentional spending decisions.
Conscious Spending: The Power of Awareness
The first and most crucial step is awareness. Start by actively tracking all your spending, no matter how small. Use budgeting apps, a notebook, or your bank’s transaction history. Seeing the numbers laid out can be a powerful motivator. Regularly review these small charges and ask yourself: “Do I truly need this? Is this purchase aligned with my goals?”
Setting Limits and Budgets: Creating Guardrails
Establish clear limits and budgets for discretionary spending. Decide how much you’re willing to spend on entertainment, subscriptions, or in-app purchases each month. When you reach that limit, stop. This creates psychological guardrails that prevent overspending. For subscriptions, conduct a monthly review to see if you’re still using them. If not, cancel them.
Delaying Gratification: The “24-Hour Rule”
When you feel the urge to make a microtransaction, implement a “24-hour rule.” Tell yourself you can have it, but you have to wait 24 hours. Often, by the time the 24 hours are up, the urge will have passed, or you’ll have had time to reconsider if it’s truly worth the money. This small delay can be incredibly effective in breaking impulsive spending habits.
Finding Alternative Rewards: Redefining Value
Identify non-monetary rewards that bring you joy and satisfaction. Instead of buying a virtual item, consider reading a book, going for a walk, spending time with loved ones, or learning a new skill. By actively seeking out and prioritizing these alternative rewards, you can reduce your reliance on microtransactions for feelings of happiness or accomplishment. This involves redefining your sense of value beyond material possessions or digital assets.
By understanding the psychological underpinnings of microtransactions, you can begin to dismantle their influence and take back control of your finances. These small purchases might seem insignificant, but the power they wield over your mind and your wallet is immense. Armed with knowledge and intentional strategies, you can navigate the world of microtransactions with a clearer mind and a healthier bank account. You have the power to make your money work for you, not the other way around.
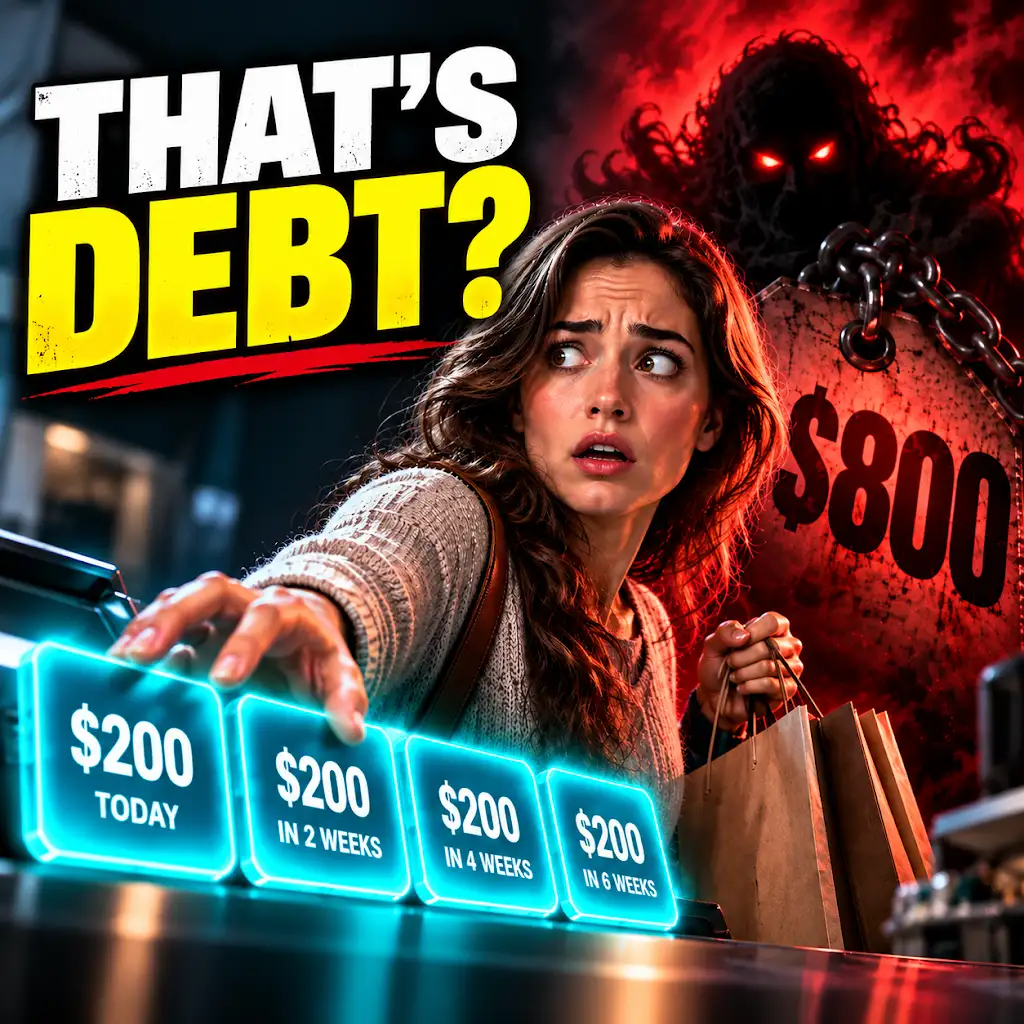
Why $800 Doesn’t Feel Like $800 Anymore
FAQs
What is the psychology behind small monthly payments?
Small monthly payments appeal to consumers because they are perceived as more manageable and less intimidating than larger lump sum payments.
How do small monthly payments influence consumer behavior?
Small monthly payments can lead to increased spending as consumers may be more willing to make purchases when they believe they can afford the monthly payments.
Are there any downsides to small monthly payments?
While small monthly payments can make purchases seem more affordable, they can also lead to overspending and accumulating debt if consumers do not carefully consider their overall financial situation.
How do small monthly payments impact budgeting and financial planning?
Small monthly payments can make it easier for consumers to budget and plan their finances as they can spread out the cost of purchases over time.
What are some strategies for managing small monthly payments effectively?
To manage small monthly payments effectively, consumers should carefully consider their budget, prioritize essential expenses, and avoid taking on more debt than they can comfortably afford to repay each month.